
TL;DR: Retirement planning in India requires defining your retirement corpus, estimating future expenses, strategically investing in a diversified portfolio across equity and debt, and regularly reviewing your progress to ensure financial security post-work.
Key Stats at a Glance:
- Average life expectancy in India: 70+ years
- Target retirement corpus for a comfortable life: ₹1 crore (estimated)
- NPS Assets Under Management (AUM): Over ₹10 lakh crore as of early 2024
- SEBI mandates a minimum investment horizon for certain retirement-focused mutual funds.
- Inflation rate in India historically averages 5-7% per annum, significantly impacting future corpus needs.
What is Retirement Planning in India?
Retirement planning in India is the process of setting financial goals for your post-working life and creating a strategy to accumulate the necessary funds to meet those goals comfortably, considering factors like inflation, healthcare costs, and lifestyle expectations.
Securing a financially independent retirement is a paramount concern for every Indian earning a livelihood. It’s not just about stopping work; it’s about ensuring you can maintain your lifestyle, cover your expenses, and pursue your interests without relying on a regular income. This requires a systematic and disciplined approach, starting long before your golden years approach.
The landscape of retirement in India has evolved significantly. With increasing life expectancies and rising living costs, simply relying on traditional savings or pension schemes is often insufficient. A well-thought-out financial plan, incorporating diverse investment avenues and regular reviews, is crucial. This guide will walk you through the essential steps to build a robust retirement corpus.
Why is Retirement Planning Crucial in India?
Retirement planning is crucial in India due to rising life expectancies, increasing healthcare costs, and the erosion of purchasing power due to inflation, necessitating a substantial corpus to maintain a desired lifestyle post-employment.
In India, individuals are living longer, healthier lives. While this is a positive development, it also means retirement funds need to last for a longer period. Compounding this challenge are the escalating costs of healthcare, which can significantly drain savings, especially in the later years. Furthermore, inflation acts as a silent wealth destroyer; ₹1 lakh today will purchase significantly less in 20-30 years. Without adequate planning, your savings might not be enough to cover even basic necessities, let alone maintain your pre-retirement lifestyle. SEBI and financial institutions consistently highlight the need for proactive planning to counter these realities.
A proactive approach ensures that your retirement is a period of enjoyment and financial freedom, rather than one of anxiety and dependence. It empowers you to live with dignity and pursue hobbies, travel, or spend quality time with family without financial constraints.
How Much Corpus is Needed for Retirement in India?
Estimating your retirement corpus involves projecting your annual expenses in retirement, multiplying it by the number of years you expect to live post-retirement, and adjusting for inflation and potential unforeseen costs.
The exact corpus needed varies significantly based on individual lifestyle, location, and health. A common rule of thumb is to aim for a corpus that can generate an annual income sufficient to cover your projected retirement expenses. Many financial advisors suggest using the ’15x rule’ or ’20x rule’ – meaning your corpus should be 15 to 20 times your estimated annual expenses in the first year of retirement. For instance, if you estimate needing ₹5 lakh annually in today’s terms, and assume it will be ₹10 lakh by retirement due to inflation, and you plan for 25 years of retirement, a corpus in the range of ₹2.5 crore to ₹3 crore might be a starting point. However, this is a simplified calculation; a detailed financial plan, perhaps aided by a financial advisor or a robust tool like Finovatives’ Trend Traders Tool (though primarily for trading, its analytical capabilities can inform long-term projections), is recommended for a precise estimate.
Factors Influencing Your Retirement Corpus
- Lifestyle Expectations: Do you plan to travel extensively, pursue expensive hobbies, or maintain a modest lifestyle?
- Healthcare Needs: Factor in potential medical expenses, considering health insurance coverage.
- Inflation: Historically, India’s inflation averages 5-7%. This significantly erodes purchasing power over time.
- Dependents: Will you have financial responsibilities towards children or elderly parents during retirement?
- Longevity: With increasing life expectancies, plan for your corpus to last at least 25-30 years.
What are the Best Investment Options for Retirement in India?
The best investment options for retirement in India involve a diversified portfolio, typically combining high-growth potential equity instruments (like mutual funds, stocks) for the long term with stable debt instruments (like PPF, fixed deposits, debt mutual funds) for capital preservation.
A balanced approach is key to wealth creation for retirement. Equity investments, particularly through well-managed mutual funds or direct stocks, offer the potential for significant capital appreciation over the long term, helping to beat inflation. For instance, Nifty 50 index funds have historically provided good returns. On the other hand, debt instruments provide stability and capital protection. Public Provident Fund (PPF) is a popular government-backed scheme offering tax benefits and assured returns. National Pension System (NPS) is another excellent government-backed option specifically designed for retirement savings, offering both equity and debt exposure with tax advantages.
The optimal mix depends on your age, risk tolerance, and time horizon. Younger investors with a longer time horizon can afford to take on more equity risk, while those closer to retirement should gradually shift towards safer debt instruments. Exploring various mutual fund categories – large-cap, mid-cap, balanced advantage funds – can help tailor the portfolio to specific needs.
Key Retirement Investment Avenues
- Equity Mutual Funds: Diversified equity funds (large-cap, flexi-cap) and index funds offer growth potential.
- National Pension System (NPS): A retirement-focused scheme with equity and debt options, offering tax benefits.
- Public Provident Fund (PPF): A long-term, tax-efficient savings scheme with fixed returns.
- Senior Citizen Savings Scheme (SCSS): For individuals above 60, offering regular income and safety.
- Fixed Deposits (FDs) & Debt Mutual Funds: For capital preservation and stable, albeit lower, returns.
- Real Estate: Can provide rental income and capital appreciation but lacks liquidity.
- Gold: Acts as a hedge against inflation and market volatility.
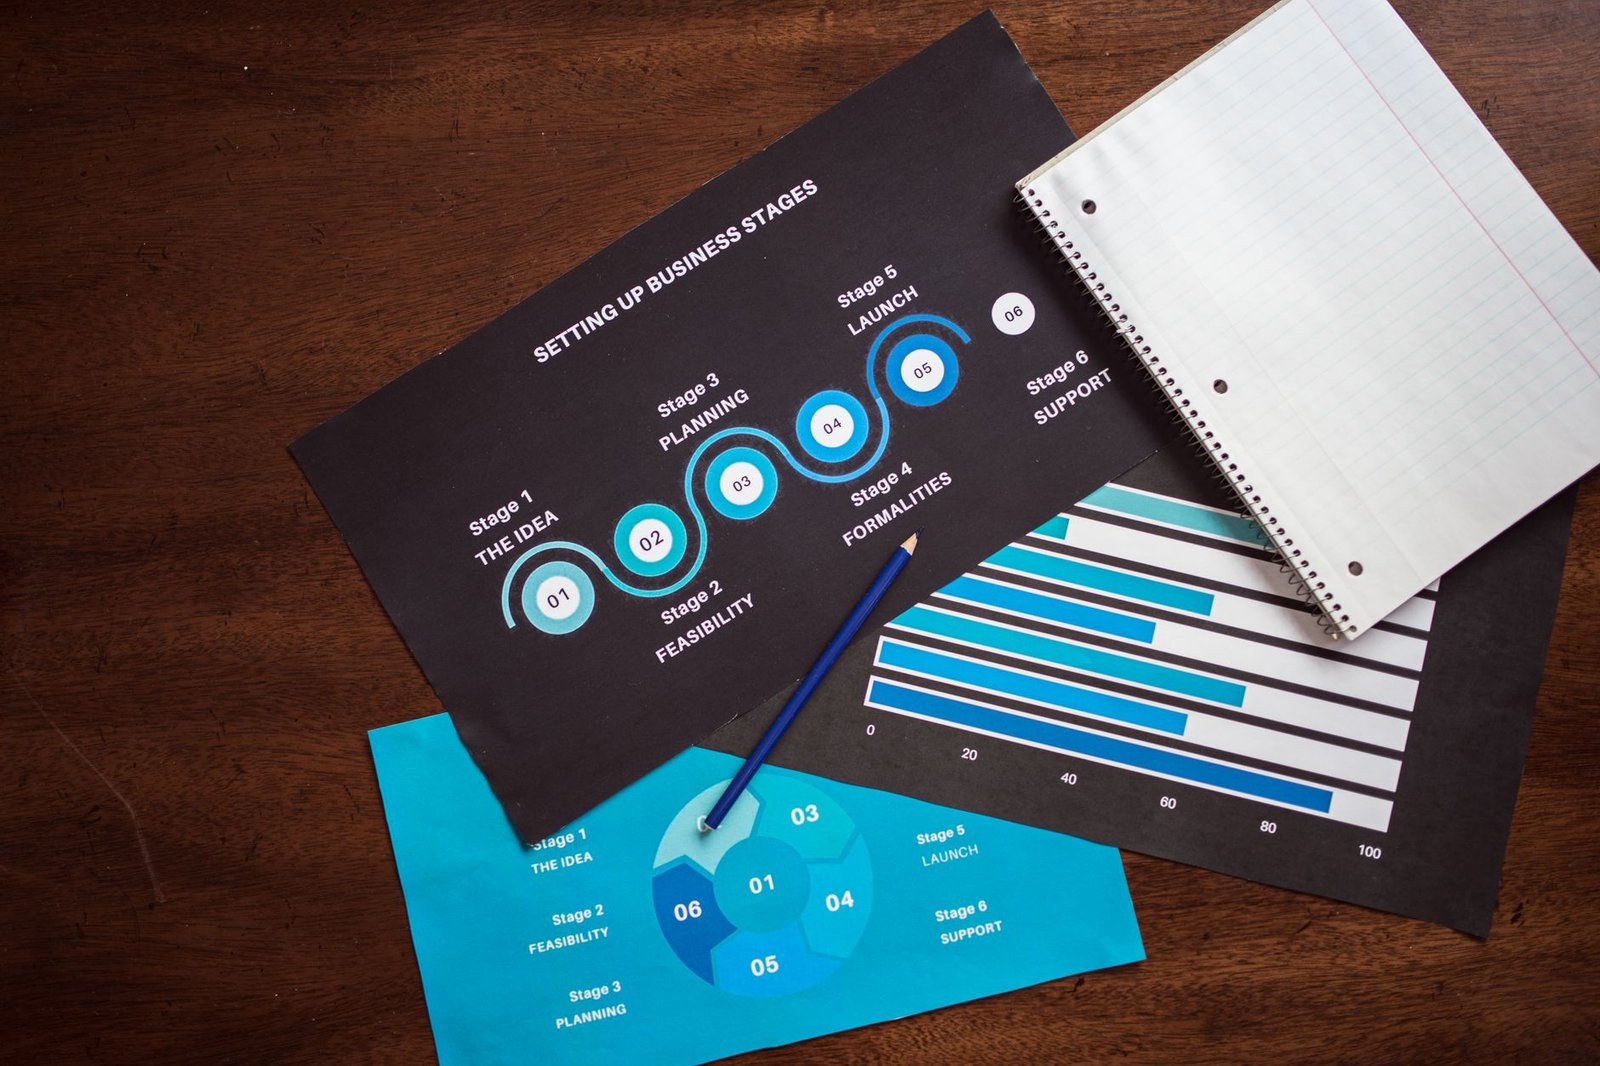
How to Create a Retirement Plan: A Step-by-Step Guide
Creating a retirement plan involves defining your retirement goals, calculating your future financial needs, choosing appropriate investment vehicles, implementing the plan, and regularly reviewing and adjusting it as per life changes and market conditions.
A concrete plan transforms the abstract idea of a secure retirement into an actionable roadmap. It ensures that your savings efforts are directed strategically, maximizing the potential for wealth creation while mitigating risks. Without a plan, financial decisions can become ad-hoc, potentially leading to shortfalls when you need the funds the most.
This structured approach helps in staying disciplined and motivated throughout your investment journey.
- Define Your Retirement Vision: Envision your life after retirement. Where do you want to live? What lifestyle do you desire? What hobbies will you pursue? This clarity sets your financial targets.
- Estimate Retirement Expenses: Project your monthly and annual expenses. Consider housing, food, healthcare, travel, entertainment, and potential emergencies. Account for inflation; a ₹50,000 monthly expense today could be ₹1.5 lakh in 30 years.
- Calculate Your Retirement Corpus: Based on projected expenses and desired retirement duration (e.g., 25 years), calculate the total lump sum needed. Use financial calculators or consult an advisor.
- Assess Your Current Financial Situation: List all your assets (savings, investments, property) and liabilities (loans, debts). Understand your net worth.
- Determine Your Risk Tolerance and Time Horizon: Your age and comfort level with market volatility will dictate your asset allocation. Younger investors can take more risk.
- Choose Investment Products: Select a mix of equity, debt, and other assets that align with your risk profile and goals. Consider NPS, PPF, mutual funds, and direct equity, keeping tax implications in mind. Explore SEBI-registered investment advisors for guidance.
- Create an Investment Strategy: Decide how much you can invest regularly (e.g., through SIPs in mutual funds) and how to rebalance your portfolio periodically.
- Implement and Monitor: Start investing as per your plan. Review your portfolio at least annually, or when significant life events occur, and rebalance if necessary to stay on track.
How to Stay on Track with Your Retirement Plan?
Staying on track with your retirement plan involves regular monitoring of your investments, adjusting your strategy based on market performance and life changes, automating savings, and maintaining discipline to avoid emotional investment decisions.
The journey to a secure retirement is a marathon, not a sprint. Market fluctuations are inevitable, and life circumstances can change. Proactive monitoring and timely adjustments are key to navigating these challenges. Automating your investments through Systematic Investment Plans (SIPs) ensures regularity and removes the temptation to skip contributions during market downturns. Seeking professional advice can provide objective insights and help you stick to your long-term goals, even when markets seem volatile. Remember, consistent effort over time is more critical than trying to time the market.
Key Strategies for Staying on Track
- Regular Portfolio Review: Check your investments at least annually to ensure they align with your goals.
- Automate Investments: Set up SIPs to ensure consistent saving and investing.
- Rebalancing: Adjust your asset allocation periodically to maintain your desired risk level.
- Avoid Emotional Decisions: Don’t panic sell during market dips or chase returns during rallies.
- Stay Informed: Keep abreast of economic changes and investment trends relevant to your portfolio.
- Seek Professional Advice: Consult a SEBI-registered financial advisor for unbiased guidance.
Frequently Asked Questions
What is the best age to start retirement planning in India?
The best age to start retirement planning is as early as possible, ideally in your early 20s. The power of compounding works best over longer periods, allowing smaller investments to grow substantially by retirement.
Should I invest in NPS for retirement?
NPS is a strong retirement-focused investment vehicle offering tax benefits and a mix of equity and debt exposure. It is particularly beneficial for those looking for a structured, long-term savings plan with a retirement objective.
How much should I save for retirement each month in India?
The amount to save monthly depends on your income, expenses, age, and target corpus. A common guideline is to save 10-15% of your income, but this may need to be higher if starting late or aiming for a very high corpus.
Is it better to invest in mutual funds or PPF for retirement?
Both have different roles. Mutual funds (especially equity funds) offer higher growth potential but also higher risk. PPF offers safety, assured returns, and tax benefits but lower growth. A combination is often ideal.
How often should I review my retirement plan?
It’s advisable to review your retirement plan at least once a year. Major life events like marriage, childbirth, or a change in income should also trigger a review and potential adjustment of your plan.
Key Takeaways:
- Start retirement planning early to leverage the power of compounding.
- Accurately estimate your retirement corpus considering inflation and lifestyle.
- Diversify investments across equity and debt instruments for balanced growth and safety.
- Consider government-backed options like NPS and PPF for their tax benefits and security.
- Regularly monitor and rebalance your portfolio to stay on track with your goals.
- Automate savings and avoid emotional investment decisions.
Investing in securities markets is subject to market risks. Read all the related documents carefully before investing. This content is for informational purposes only and does not constitute financial advice.

 Finovatives