
TL;DR: Reading financial statements of Indian companies involves analysing the Balance Sheet (assets, liabilities, equity), the Profit & Loss (P&L) statement (revenue, expenses, profit), and the Cash Flow statement (operating, investing, financing activities) to gauge financial health and predict future performance for trading decisions.
Key Stats at a Glance:
- NSE listed companies: Over 2,000+
- BSE listed companies: Over 5,000+
- Average FY profit growth for Nifty 500 companies: 15-20% (varies annually)
- SEBI mandates quarterly financial reporting for listed entities
- Companies Act, 2013 governs financial reporting standards in India
What are Financial Statements?
Financial statements are formal records of the financial activities and position of a business, person, or other entity, providing a structured overview of financial performance and health over specific periods.
For Indian retail traders and investors, these documents are the bedrock of fundamental analysis, offering objective data to move beyond speculative trading. They are mandated by SEBI for all listed companies and are typically released quarterly and annually. The primary statements to focus on are the Balance Sheet, the Profit & Loss (P&L) Statement, and the Cash Flow Statement. Understanding these allows you to assess a company’s financial stability, profitability, and liquidity – key factors in making sound investment or trading decisions.
These statements are prepared in accordance with Indian Accounting Standards (Ind AS) or Accounting Standards (AS) notified under section 133 of the Companies Act, 2013. While the data can seem daunting, breaking it down into its core components makes it manageable.
How to Analyse the Balance Sheet?
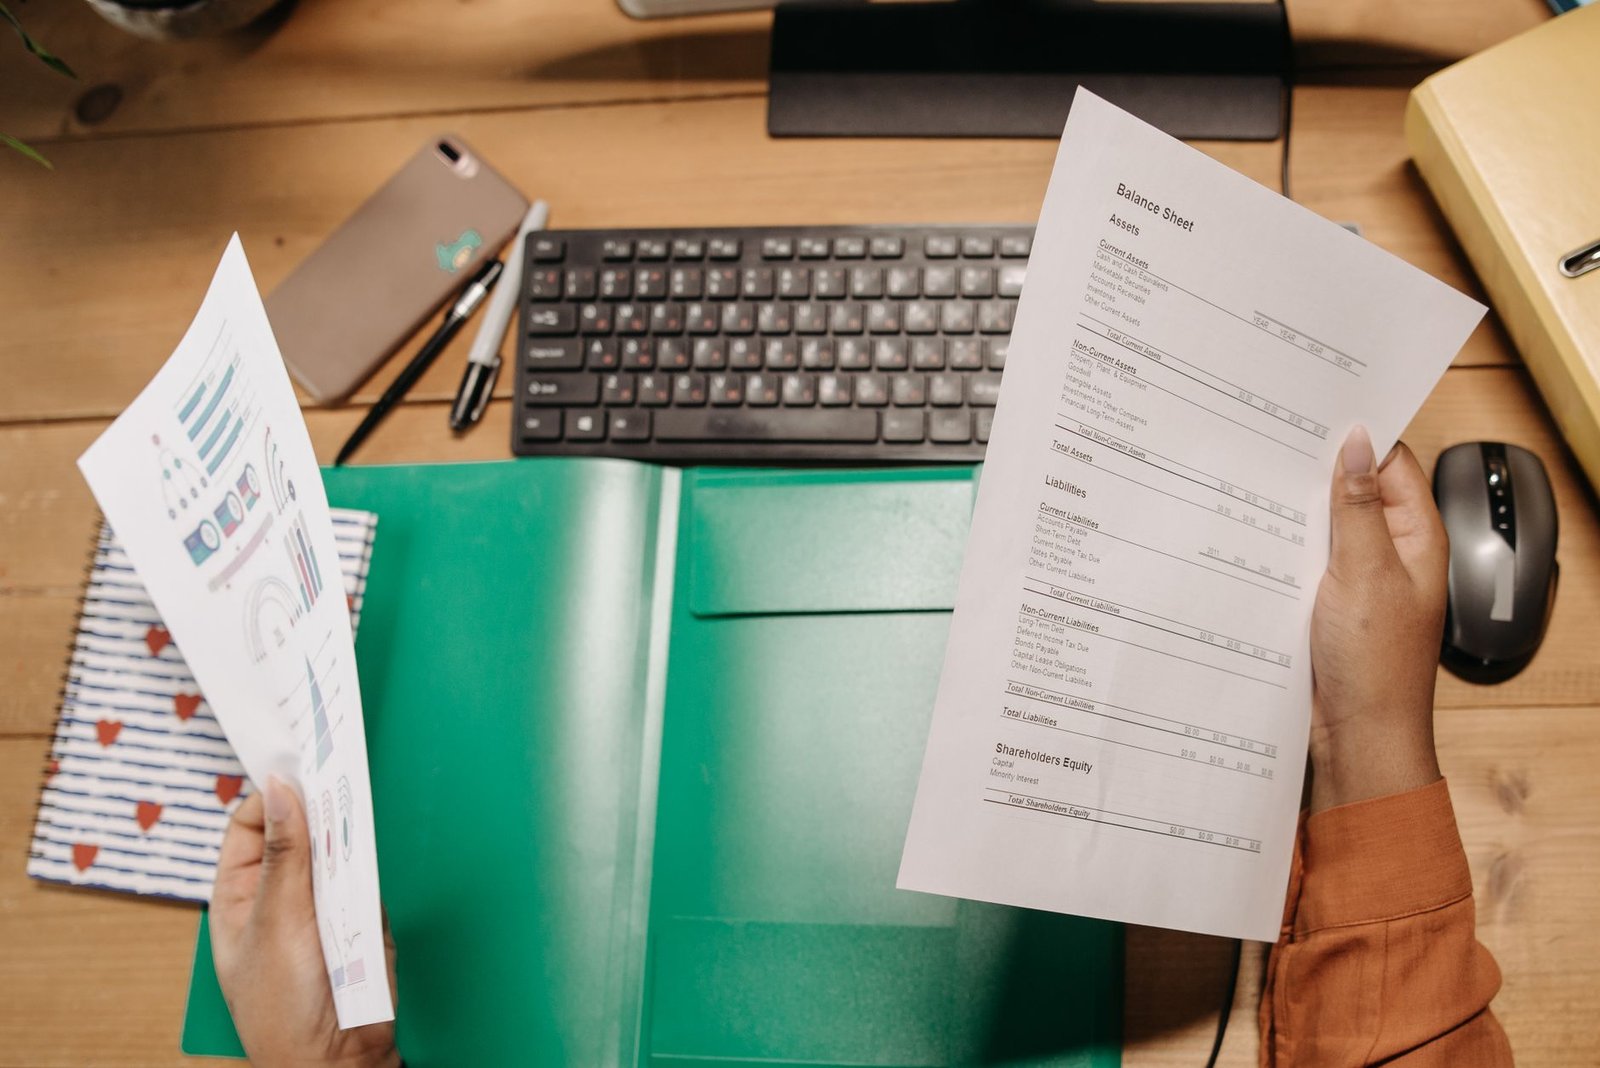
The Balance Sheet provides a snapshot of a company’s financial position at a specific point in time, detailing its assets, liabilities, and shareholders’ equity.
Often referred to as the ‘statement of financial position’, the Balance Sheet follows the fundamental accounting equation: Assets = Liabilities + Equity. It tells you what a company owns (assets), what it owes (liabilities), and the owners’ stake (equity). For traders, analysing trends in these components can highlight financial strength or potential red flags. For instance, a consistent increase in assets coupled with controlled liabilities suggests healthy growth. Conversely, rapidly rising debt levels might signal financial distress.
Understanding Assets
Assets are resources owned by the company that have economic value and are expected to provide future benefits. They are typically categorised into current assets (expected to be converted to cash within a year, like inventory, cash, accounts receivable) and non-current assets (long-term assets, like property, plant, equipment, intangible assets).
Understanding Liabilities
Liabilities represent what the company owes to external parties. They are divided into current liabilities (due within a year, such as accounts payable, short-term loans) and non-current liabilities (long-term obligations, like bonds, long-term debt).
Understanding Equity
Shareholders’ equity represents the owners’ residual claim on the assets of the company after deducting liabilities. It includes share capital, reserves, and retained earnings. It signifies the company’s net worth.
Key Ratios from the Balance Sheet
Several ratios derived from the Balance Sheet offer crucial insights:
- Current Ratio: Current Assets / Current Liabilities. A ratio above 1.5-2 generally indicates good short-term liquidity.
- Debt-to-Equity Ratio: Total Liabilities / Shareholders’ Equity. A lower ratio is generally preferred, indicating less reliance on debt financing. A ratio above 1 might suggest higher financial risk.
- Working Capital: Current Assets – Current Liabilities. Positive working capital is essential for day-to-day operations.
Analysing the trend of these ratios over multiple periods is more insightful than a single snapshot. For example, a rising Debt-to-Equity ratio over several quarters warrants closer scrutiny.
How to Read the Profit & Loss (P&L) Statement?
The Profit & Loss statement, also known as the Income Statement, reports a company’s financial performance over a specific period, showing its revenues, expenses, and resulting profit or loss.
The P&L statement is a dynamic report that shows how much money a company made (revenue) and how much it spent (expenses) over a period, typically a quarter or a year. The bottom line – net profit or loss – is what often grabs headlines, but understanding the components is vital for a trader. A consistently growing revenue stream and improving profit margins are strong indicators of a healthy business. Conversely, declining revenues or shrinking margins can signal underlying problems.
Revenue/Sales
This is the top line – the total income generated from the company’s primary business activities (selling goods or services). It’s crucial to look at the growth rate of revenue over time.
Cost of Goods Sold (COGS)
These are the direct costs attributable to the production of the goods or services sold by the company. Comparing revenue growth to COGS growth helps assess operational efficiency.
Gross Profit
Calculated as Revenue minus COGS. This shows the profit a company makes before accounting for operating expenses, interest, and taxes.
Operating Expenses
These are costs incurred in the normal course of business operations, not directly tied to production. They include selling, general, and administrative (SG&A) expenses, marketing, R&D, etc.
Operating Profit (EBIT)
Earnings Before Interest and Taxes. This reflects the profitability of the core business operations. It’s a key metric to understand the efficiency of management in generating profits from sales.
Net Profit
The bottom line. After deducting all expenses, including interest and taxes, the remaining profit is the net profit available to shareholders. Analysing Net Profit Margin (Net Profit / Revenue) provides insight into profitability efficiency.
Key Ratios from the P&L Statement
- Gross Profit Margin: (Gross Profit / Revenue) * 100. Shows efficiency in production.
- Operating Profit Margin: (Operating Profit / Revenue) * 100. Shows profitability from core operations.
- Net Profit Margin: (Net Profit / Revenue) * 100. Shows overall profitability after all expenses.
- Earnings Per Share (EPS): (Net Profit – Preferred Dividends) / Average Outstanding Shares. A fundamental measure of profitability per share.
Consistent improvement in these margins, especially operating and net profit margins, is a positive sign. Comparing these margins to industry peers also provides valuable context.
How to Interpret the Cash Flow Statement?
The Cash Flow Statement tracks the movement of cash both into and out of a company over a period, categorised into operating, investing, and financing activities.
While the P&L shows profitability on an accrual basis (recognising revenue when earned, not necessarily when cash is received), the Cash Flow Statement focuses purely on cash. A company can be profitable on paper but still struggle with cash. This statement reveals the actual cash generated and used by the business, making it indispensable for assessing liquidity and financial health. Positive cash flow from operations is a strong indicator of a sustainable business model. Traders often use this to identify companies with strong cash generation capabilities, which can support dividends and growth initiatives.
Cash Flow from Operating Activities (CFO)
This section shows the cash generated or used from the normal day-to-day business operations. Positive CFO is crucial as it indicates the core business is generating enough cash to sustain itself and potentially fund growth or pay debts. It starts with Net Income and adjusts for non-cash items (like depreciation) and changes in working capital.
Cash Flow from Investing Activities (CFI)
This section reflects cash spent or received from the purchase or sale of long-term assets and other investments. Buying new equipment or property results in negative CFI, while selling assets results in positive CFI.
Cash Flow from Financing Activities (CFF)
This section details cash flows related to debt, equity, and dividends. Issuing stock or taking loans brings cash in (positive CFF), while repaying debt, buying back stock, or paying dividends uses cash (negative CFF).
Free Cash Flow (FCF)
While not a separate section in the main statement, FCF is a critical derived metric. It’s typically calculated as CFO minus Capital Expenditures (CapEx, found in CFI). FCF represents the cash available to the company after all necessary investments in operations and assets are made. It can be used for debt repayment, dividends, or further expansion.
How to Read Financial Statements
- Obtain the Statements: Download the latest quarterly and annual reports (from NSE/BSE websites or company investor relations pages) for the companies you are interested in.
- Analyse the Balance Sheet: Review assets, liabilities, and equity. Calculate key ratios like Current Ratio and Debt-to-Equity ratio to assess financial health and leverage.
- Examine the P&L Statement: Track revenue growth, analyse profit margins (Gross, Operating, Net), and check Earnings Per Share (EPS) trends.
- Scrutinise the Cash Flow Statement: Focus on positive Cash Flow from Operations (CFO). Calculate Free Cash Flow (FCF) to understand cash available for discretionary uses.
- Compare with Previous Periods: Analyse trends over at least 3-5 periods (quarters or years) to identify consistent performance or emerging issues.
- Benchmark Against Industry Peers: Compare key ratios and growth rates with competitors to understand relative performance.
- Read the Management Discussion & Analysis (MD&A): This section within the annual report provides management’s perspective on performance, risks, and future outlook.
- Look for Red Flags: Watch for consistently declining revenues, deteriorating margins, increasing debt without corresponding asset growth, or negative operating cash flow.
Frequently Asked Questions
What is the most important financial statement for a trader?
While all are important, the Cash Flow Statement is often considered vital for traders as it shows the actual cash a company is generating and using, crucial for assessing liquidity and sustainability beyond reported profits.
How often should I check financial statements?
Listed Indian companies report quarterly. Traders should review these quarterly results promptly, supplemented by annual reports for a comprehensive view, especially before making significant investment decisions.
What are some common red flags in financial statements?
Declining revenue, shrinking profit margins, a high and increasing debt-to-equity ratio, negative cash flow from operations, and significant one-time gains masking recurring losses are common red flags.
Where can I find financial statements for Indian companies?
You can find them on the websites of stock exchanges like the NSE (National Stock Exchange) and BSE (Bombay Stock Exchange), or directly on the investor relations sections of the respective company websites.
How do financial statements help in technical analysis?
While technical analysis focuses on price charts, understanding financial statements provides fundamental context. Strong financials can support bullish technical patterns, while weak financials might warn of upcoming price declines, even if charts look promising.
Can I use financial statements for short-term trading?
Yes, especially quarterly results and news related to them. Significant deviations from expectations in revenue or profit can cause short-term price movements. However, a deep understanding is needed to interpret the impact correctly.
Key Takeaways
- Financial statements (Balance Sheet, P&L, Cash Flow) are essential tools for fundamental analysis by Indian traders.
- The Balance Sheet shows a company’s assets, liabilities, and equity at a point in time.
- The P&L statement details revenues, expenses, and profits over a period.
- The Cash Flow statement tracks the actual movement of cash in and out of the business.
- Key ratios and trend analysis over multiple periods provide deeper insights than single data points.
- Always compare a company’s performance against its historical data and industry peers.
- Look for consistency in revenue growth, healthy profit margins, and strong positive cash flow from operations.
Investing in the stock market involves inherent risks, and financial statements are just one tool for analysis. Past performance is not indicative of future results.


 Finovatives