
TL;DR: A Systematic Investment Plan (SIP) is generally better for most Indian investors due to rupee cost averaging, discipline, and reduced market timing risk, especially in volatile markets. Lump sum investing is suitable for experienced investors with significant capital and a high conviction in market timing.
Key Stats at a Glance:
- Average SIP investment in Indian mutual funds: ₹8,000-10,000 per month (as of recent reports).
- Nifty 50’s highest single-day gain: 13.14% (March 24, 2020).
- Nifty 50’s largest single-day fall: 12.97% (March 23, 2020).
- Estimated 10-year CAGR for diversified equity mutual funds: 12-15% (historical averages, not guaranteed).
- Number of Demat accounts in India: Over 100 million (as of early 2024).
What is a Systematic Investment Plan (SIP)?
A Systematic Investment Plan (SIP) is a method of investing a fixed amount of money at regular intervals, typically monthly, into a chosen mutual fund scheme.
This disciplined approach allows investors to accumulate wealth over the long term by investing small amounts consistently. SIPs are particularly beneficial in Indian markets, which are known for their volatility. By investing a fixed sum regularly, you buy more units when market prices are low and fewer units when prices are high, a concept known as rupee cost averaging.
The inherent discipline of SIPs helps investors avoid emotional decision-making, a common pitfall. Instead of trying to time the market – a notoriously difficult task even for seasoned professionals – SIPs ensure continuous investment regardless of market fluctuations. SEBI regulations mandate clear disclosures about fund performance and expenses, empowering investors.
Benefits of SIP
- Rupee Cost Averaging: Reduces the average cost per unit over time.
- Disciplined Investing: Encourages regular savings and wealth creation.
- Mitigates Volatility Risk: Less impact from short-term market swings.
- Accessibility: Allows investment with small amounts, starting from ₹500.
- Power of Compounding: Early and consistent investment magnifies returns over time.
Drawbacks of SIP
- Potentially Lower Returns in Bull Runs: May lag lump sum if the market experiences a sharp, sustained upward trend immediately after investment.
- Limited Benefit from Market Timing: Does not capitalize on sharp downturns for large purchases.
What is a Lump Sum Investment?
A lump sum investment involves investing a single, large amount of money into an investment vehicle at one time.
This strategy is often considered by investors who have a significant sum available and believe they have accurately predicted a favourable market condition or entry point. In the Indian context, this could mean investing a large bonus, inheritance, or savings all at once into a mutual fund, stock, or other financial instrument. The success of a lump sum investment heavily relies on market timing – investing at the right moment can yield substantial profits, while the opposite can lead to significant losses.
Benefits of Lump Sum
- Potential for Higher Returns: If invested at a market low, it can capture the entire subsequent rally.
- Simplicity: A one-time decision and transaction.
- Full Benefit of Compounding: The entire sum starts compounding from day one.
Drawbacks of Lump Sum
- High Market Timing Risk: Investing at a market peak can lead to substantial immediate losses.
- Emotional Impact: A large initial loss can be psychologically devastating.
- Requires Significant Capital: Not feasible for investors with limited funds.
- Missed Opportunities: If the market moves up significantly after a missed investment window.
SIP vs Lump Sum: Which Strategy is Better for You?
The choice between SIP and Lump Sum hinges on your financial goals, risk tolerance, investment horizon, and market outlook.
For the majority of Indian retail investors, particularly those new to investing or with moderate risk appetites, SIP is the recommended route. The disciplined, regular investment approach helps build wealth steadily while cushioning the impact of market volatility. It aligns well with the long-term wealth creation objective that most investors seek. However, if you possess substantial capital, a deep understanding of market cycles, and a strong conviction about an impending market rise, a lump sum investment might be considered, albeit with caution.
Factors to Consider
- Risk Tolerance: SIPs are lower risk due to averaging; lump sums are higher risk.
- Investment Horizon: Both work for long-term, but SIPs provide consistency.
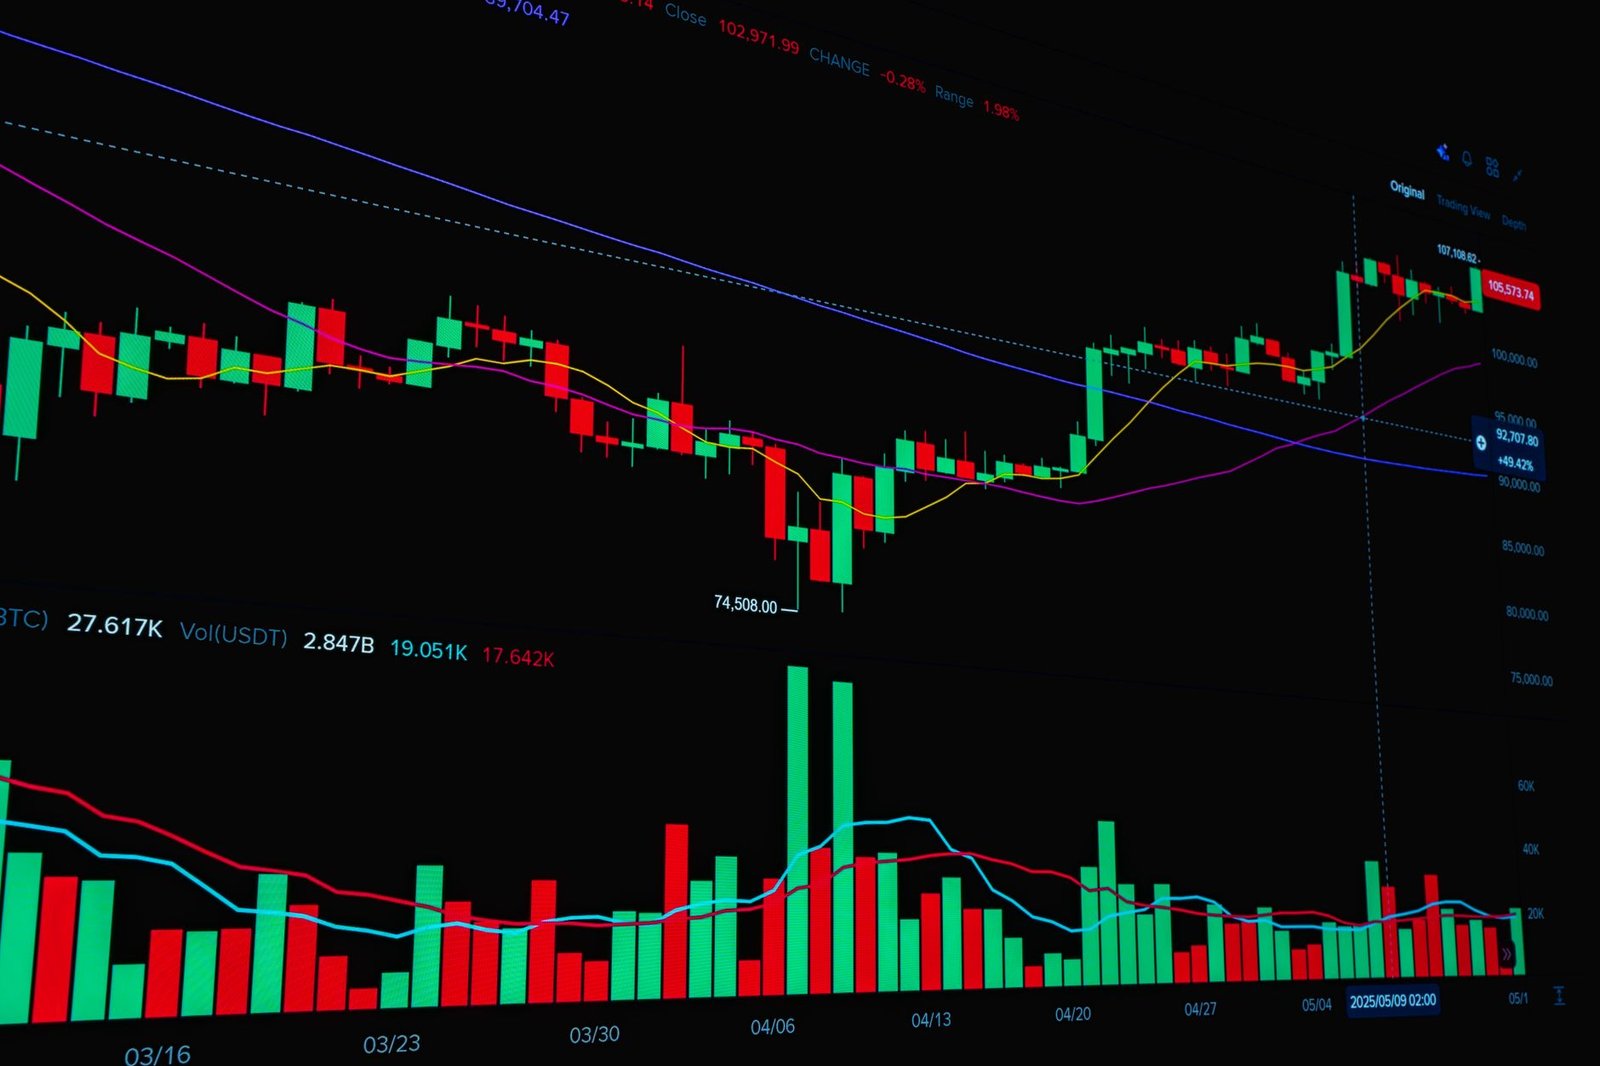
- Market Conditions: SIPs are safer in volatile or uncertain markets. Lump sums can be rewarding in clearly identified bull phases but risky otherwise.
- Available Capital: SIPs are accessible with small amounts; lump sums require significant funds.
- Investment Knowledge: SIPs are beginner-friendly; lump sums require more market insight.
How to Choose Between SIP and Lump Sum
Selecting the right investment strategy requires careful consideration of your personal financial situation and market dynamics. Here’s a step-by-step guide:
- Define Your Financial Goals: Clearly outline what you are saving for (e.g., retirement, down payment, child’s education) and your target corpus.
- Assess Your Risk Tolerance: Determine how much market fluctuation you can comfortably handle. If you are risk-averse, lean towards SIP.
- Evaluate Your Investment Horizon: Longer horizons (10+ years) generally favour SIPs for consistent wealth building. Shorter horizons might require different strategies.
- Analyze Market Conditions: If markets are at perceived highs, SIPs are safer. If markets have corrected significantly and you have conviction, a staggered lump sum (investing over a few weeks) might be considered.
- Determine Your Available Capital: If you have a large sum readily available, you can consider lump sum or a phased SIP setup. If you earn regularly, SIP is more practical.
- Consider Professional Advice: Consult a SEBI-registered investment advisor to understand which approach best suits your profile.
- Start Investing: Once decided, initiate your investment either through a regular SIP mandate or by making a lump sum transfer.
Can You Do Both SIP and Lump Sum?
Yes, it is entirely possible and often strategically sound to employ both SIP and lump sum investments concurrently.
Many investors choose to maintain a regular SIP for their ongoing investments to benefit from rupee cost averaging and discipline. Simultaneously, they might deploy a lump sum when they have additional funds available and perceive a favourable market opportunity, or when a specific financial windfall occurs. This hybrid approach allows investors to harness the benefits of both strategies – the consistency and risk mitigation of SIPs, combined with the potential for enhanced returns from timely lump sum deployments. This is where advanced tools can help monitor your portfolio and suggest optimal entry points.
Frequently Asked Questions
Is SIP better than lump sum for beginners?
Yes, SIP is generally better for beginners. It instils discipline, allows investment with small amounts, and mitigates the risk of investing at a market peak.
Can I get higher returns with a lump sum?
Potentially, yes. If you invest a lump sum at a market low, you can capture a larger portion of the subsequent rally, leading to higher returns compared to a staggered SIP.
What if I invest a lump sum and the market crashes?
If the market crashes after a lump sum investment, you will experience significant immediate losses. A SIP would have averaged your purchase cost, reducing the impact.
When should I consider a lump sum investment?
Consider lump sum when you have a large amount of money, believe the market is undervalued, and have a long-term investment horizon with a high-risk tolerance.
How can I decide the amount for my SIP?
Calculate your financial goal, investment horizon, and expected returns. Use SIP calculators available online, considering inflation and potential fund performance, to determine a suitable SIP amount.
What is Systematic Transfer Plan (STP)?
STP is a facility where you invest a lump sum in a liquid or low-risk fund and systematically transfer a fixed amount into an equity or other chosen fund at regular intervals, combining lump sum flexibility with SIP discipline.
Key Takeaways:
- SIP offers rupee cost averaging, discipline, and risk mitigation, making it ideal for most Indian investors.
- Lump sum investing offers potential for higher returns but carries significant market timing risk.
- The best strategy depends on individual risk tolerance, goals, and market outlook.
- A hybrid approach combining SIP and lump sum can be effective.
- Consistency and discipline are crucial for long-term wealth creation, often best achieved through SIPs.
- Always consult SEBI guidelines and consider professional advice before investing.
Investment in securities markets are subject to market risks. Read all the related documents carefully before investing. Past performance is not indicative of future results.

 Finovatives